If an accident occurs on your property, your mind will race toward the details of your Scottsdale, AZ home insurance policy. However, home insurance coverage has limits.
What happens when those limits are exceeded?
Umbrella insurance saves the day. However, if you have home insurance without the backup protection of umbrella insurance, you run the risk of exhausting your policy’s coverage and paying the rest out of pocket.
Accidents at Your Property
Most home insurance policies have standard personal liability coverage limits capped at a couple hundred thousand dollars. In the event that an accident at your property surpasses those limits, you’ll need umbrella insurance.
This way, a slip and fall, pool accident or dog bite at your property won’t bankrupt you or deplete your savings. Instead, you’ll tap into the umbrella insurance after your home insurance limits are surpassed.
The Lifesaver Insurance You’ve Been Looking For
It all boils down to this: you shouldn’t have to pay out of pocket when conventional home insurance hits its limit. However, such scenarios are quite possible.
Instead of subjecting your personal finances to the risk of an injured party litigating to pursue the balance beyond home insurance limits, be smart. Choose umbrella insurance and you’ll rest easy knowing you have additional coverage applicable when the primary policy runs out of coverage.
Alliance Insurance Partners is on Your Side
If you are considering umbrella insurance, do your due diligence. Give Alliance Insurance Partners a call at 602-427-4300 to learn more about umbrella insurance coverage. We serve the entirety of the greater Scottsdale, AZ area.
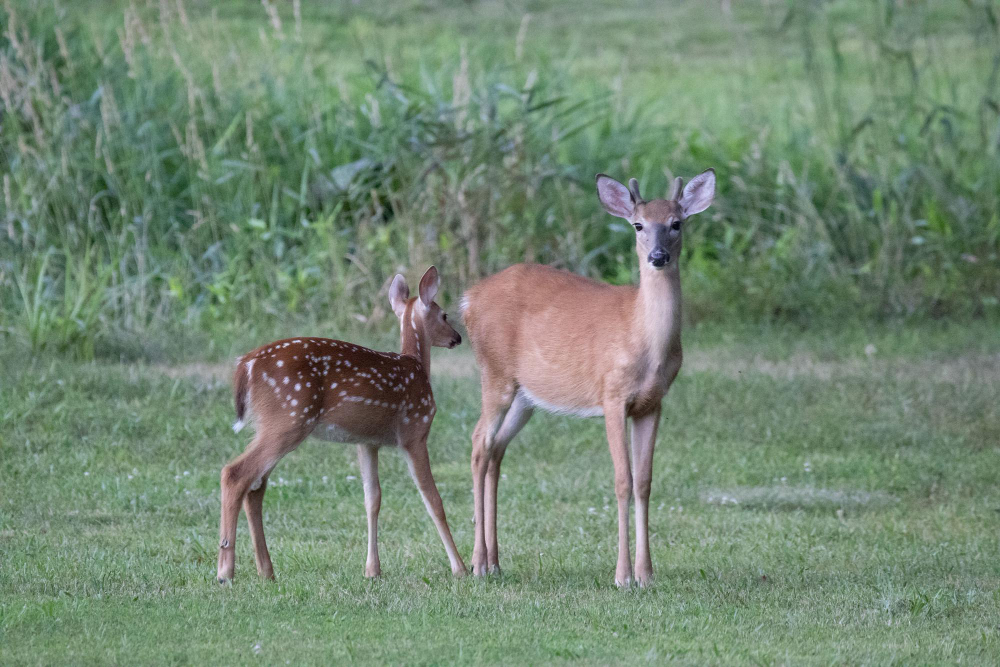
Experiencing a deer collision on Michigan roadways can be unsettling. A clear understanding of how a typical auto insurance policy handles such incidents helps drivers navigate the claims process with confidence and minimizes surprises when the time comes to file a claim.
What happens when you hit a deer?
In Michigan, when a vehicle strikes a deer or the animal causes damage to your car, the loss is generally processed as a comprehensive claim, provided you carry comprehensive coverage. This portion of a policy is designed to address damage not caused by a collision with another vehicle or object.
Comprehensive coverage protects against non-collision perils such as animal strikes, theft, vandalism, fire, and certain weather-related damage.
If your policy includes comprehensive coverage, damage from a deer encounter is typically covered after your deductible is satisfied, subject to policy terms and limits.
What does comprehensive coverage pay for after a deer accident?
When a deer accident falls under comprehensive coverage, the policy may contribute toward repairs to your vehicle after the deductible is met.
Example perspective: If a vehicle sustains $5,000 in damage and you have a $500 deductible for comprehensive, you would generally be responsible for the first $500, with the insurer covering the remainder per the policy terms.
Total loss scenarios may result in a settlement based on the vehicle’s value and policy provisions, less any applicable deductible.
Important caveat: coverage limits, deductibles, exclusions, and settlement provisions vary by policy. A driver should review their own policy for precise figures and conditions.
What if you swerve to avoid a deer and collide with another object?
If you swerve to avoid a deer and then strike a tree, guardrail, another vehicle, or another object, the resulting damage may be treated as a collision claim rather than a comprehensive claim.
Collision coverage and comprehensive coverage can have different deductibles, which can influence the out-of-pocket expense.
The determination of which coverage applies can depend on the specifics of the incident and the insurer’s guidelines.
What does your Michigan auto policy not cover after a deer incident?
While comprehensive coverage provides meaningful protection, several areas may fall outside its scope or require separate considerations.
Injuries: Damage to the vehicle and injuries to people are addressed under different portions of an auto insurance policy. Michigan’s no-fault framework and medical coverage may influence how injuries are handled, and policy specifics matter.
Personal belongings: Items inside the vehicle, such as laptops, purses, or electronics, are generally not covered by comprehensive auto coverage and may require other insurance or riders.
Deductibles: Even when losses are covered, the deductible remains the policyholder’s responsibility. Higher deductibles can lower premiums but increase out-of-pocket costs when filing a claim.
Does hitting a deer affect insurance rates?
Premium impacts depend on policy structure and insurer practices. Because a deer incident is typically treated as a comprehensive claim, it is not the same as at-fault collision claims. Nevertheless, insurers may consider various factors when adjusting rates, and outcomes can differ by carrier and individual circumstances.
Consulting your insurance agent can provide guidance on how your carrier handles comprehensive claims and potential rate implications.
What should you do after a deer accident?
The primary concern is safety, followed by appropriate reporting and documentation.
Move to a safe location and use hazard lights if possible.
Check yourself and passengers for injuries; seek medical attention if needed.
Report the incident to law enforcement when appropriate.
Avoid approaching an injured deer.
Document the scene with photos of the vehicle, damage, and surroundings if safe to do so.
Contact your insurer or agent to report the claim and outline next steps.
Arrange for inspections or repairs through the insurer’s approved process.
Review your coverage before you need it
Proactive policy review helps Michigan drivers understand what is covered in the event of a deer encounter.
Confirm whether you carry comprehensive and/or collision coverage, and verify deductible amounts.
Understand limits, exclusions, and any endorsements that affect coverage for animal-related damage.
Engage with your insurance agent to interpret policy terms in clear, straightforward terms.
Final takeaway
If you experience a deer-related incident, comprehensive coverage generally addresses the resulting damage to the vehicle, subject to deductible and policy terms. If a swerving scenario leads to a collision with another vehicle or object, collision coverage may apply instead. Because coverage details vary by policy, reviewing the terms in advance remains one of the best practices to avoid surprises when you file a claim.